

Self-Employed Mortgage Broker serving Alberta & British Columbia
I'm Owen Langis, a licensed mortgage broker helping self-employed business owners across Alberta and British Columbia qualify for mortgages. I specialize in working with incorporated business owners, contractors, and sole proprietors using lenders that consider corporate income, dividends, business write-offs, and alternative income programs when traditional banks fall short.
100% Free Review • No Obligation • Questions Answered
What Our Customers Say

Check Out Our Awards and Media Mentions
We're grateful to be featured by respected publications and organizations that highlight trusted professionals in the community.
Top 10 Mortgage Broker
DailyHive - Business Owner Mortgages
The Best Mortgage Brokers
Clever Canadian - Top Mortgage Brokers
Get in Touch
Let’s Find the Best Mortgage for You
A short discovery call is all it takes to start. We'll review your situation, walk through your options, and give you a clear picture of what's possible.
Call or Text
(403) 968-8512
owen@mortgageconnection.ca
Schedule a call
Book a call for a time that works best for you
See What Self-Employed Mortgage Option Is Best for You
Why getting a mortgage can be different when you're self-employed
A profitable business does not always produce a straightforward mortgage application.
Tax deductions reduce reported income
Legitimate expenses can lower taxable income. Some lenders may consider eligible add-backs or other documented income calculations.
Business income stays in the corporation
Incorporated owners may take a modest salary or dividends while leaving earnings in the business. Certain programs can assess more than personal income alone.
Earnings change year to year
Contractors, commission earners and seasonal business owners may have variable income. Lenders often examine history, stability and supporting documents.
My approach: Review how you earn income, understand your tax and business records, then compare lenders whose underwriting rules suit your situation. No program guarantees an approval.
Mortgage services for every stage of homeownership
Each service has its own eligibility questions, documentation and lender considerations. Choose the guide that matches what you're planning to do.
Buying a home
Self-Employed Mortgage Pre-Approval
Understand your realistic purchase budget before making an offer. We review personal tax returns, corporate financials, credit and down-payment funds, then assess suitable lender programs.
First Purchase
First-Time Home Buyers
Buying your first home while self-employed? Learn how income verification, down payments, closing costs and available buyer programs affect your mortgage plan.
Existing homeowners
Mortgage Renewal
Your mortgage term is ending. Learn when income must be requalified, how lender switches work and why the lowest advertised rate is not always the best choice.
Credit challenges
Bad Credit Mortgages
A low credit score, missed payments or past credit issues don't automatically mean you can't qualify for a mortgage. Explore alternative lenders and mortgage programs designed for borrowers rebuilding their credit.
Access home equity
Mortgage Refinance
Explore refinancing for renovations, debt consolidation, investments or business needs. We compare equity, debt-service ratios, penalties and available lenders.
Second opinion
Declined by Your Bank?
Being declined by one bank doesn't mean every lender will say no. Different lenders assess self-employed income, business expenses and credit differently. Find out what other mortgage options may be available.
Explore mortgage options after a bank decline
How do lenders calculate self-employed mortgage income?
There is no universal self-employed income formula. The available calculation depends on the lender, mortgage insurance rules, business history and documentation.
Two-year tax-return average
Many lenders start with income reported on your personal T1 returns and Notices of Assessment. They may average two years, assess a trend or apply their own stability rules.
Eligible business expense add-backs
Some lenders permit specified expenses to be added back when supported by financial statements and program rules. Not every expense qualifies.
Income gross-up
Some lender programs adjust eligible self-employed income using a prescribed gross-up. The percentage and qualifying conditions differ by lender.
Salary and dividends
Incorporated owners may receive T4 salary, T5 dividends or both. Lenders verify the income and determine whether it is sustainable.
Corporate financial statement review
Certain programs can consider company profits, cash flow and retained earnings. Ownership, liquidity, debt and accountant-prepared statements may matter.
Alternative or stated-income programs
Where traditional documentation does not reflect the business, some lenders may consider supportable alternative income evidence, usually with different pricing or equity requirements.
Mortgage Programs
Find the mortgage program that fits how you earn
Stated-Income Mortgages
For eligible business owners whose reported taxable income may not fully represent their supportable earning capacity.
New Business Mortgages
Options for newer self-employed borrowers depend on prior experience, business continuity, credit and down payment.
Incorporated Business Owner Mortgages
Understand how lenders may review corporate earnings, shareholder compensation and financial statements.
Explore incorporated-owner qualification
Income Gross-Up
Some programs allow an eligible adjustment to qualifying income, depending on the lender's guidelines.
Income Add-Back Programs
See why some eligible business expenses may be considered in addition to tax-return income.
Alternative Lending
Compare prime, alternative and private lending approaches, including differences in qualification, rates and fees.
Compare mortgage lender approaches
What to prepare
Documents commonly needed for a self-employed mortgage
Sole proprietors and contractors
- Two years of full personal T1 General returns and NOAs
- Two years T2125 statement of business activity
- Bank statements or invoices if requested
- Down-payment and credit documentation
Incorporated business owners
- Two years of full personal T1 General returns and NOAs
- Corporate T2 returns and corporate NOAs, if requested
- Two years of accountant-prepared financial statements with notice to reader
- Bank statements or invoices if requested
- Business ownership and incorporation documents
- Down-payment and credit documentation
These are typical examples, not a universal checklist. Your lender may request additional documents
WE WORK WITH CANADA'S TOP SELF-EMPLOYED MORTGAGE LENDERS
TD Canada Trust | Scotiabank | First National | RMG Mortgages | National Bank
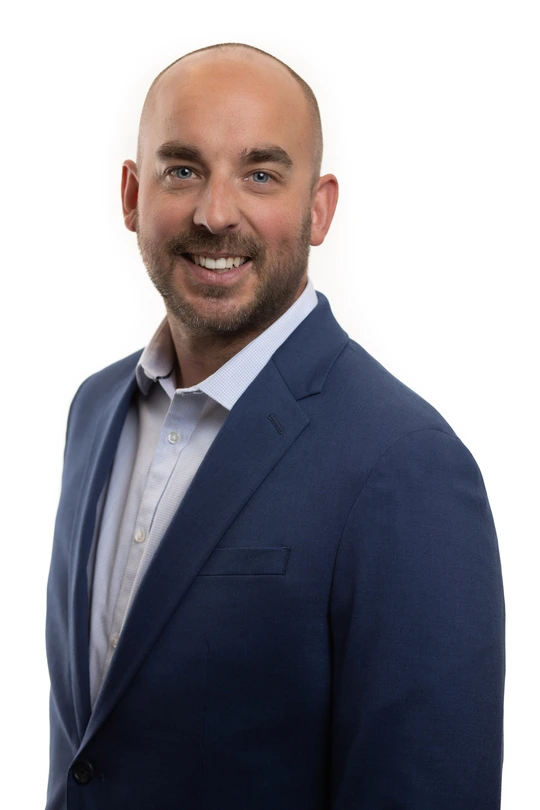
Meet Owen — Self-Employed Mortgage Broker
Getting a mortgage when you’re self-employed can be tricky - especially when your income doesn’t fit the bank’s standard rules. I’m Owen, a licensed mortgage broker and I am focused on helping business owners in Alberta & British Columbia get approved using lenders and programs that understand how self-employed income really works. I work with major banks, credit unions, and flexible lenders to find the right fit - whether you are a long time successful business owner, newly self-employed, have write-offs, or have been declined before.
Business owners I help
Self-employed income comes in many forms.
Your industry matters, but your business structure, income history, credit, down payment and documentation matter more.
Incorporated Business Owners
T2 filers with retained earnings, complex income flows, and corporate structures
Commission Earners
Real estate agents, financial advisors, and sales professionals with variable income structures
Oil & Gas Consultants
Incorporated contractors and consultants in Alberta & British Columbia's energy sector - A common self-employed profile in Western Canada
Healthcare Professionals
Dentists, physicians, physiotherapists, and allied health professionals with practice income
Trades & Construction
Electricians, plumbers, general contractors, and tradespeople running their own companies
Tech & Consulting
Freelancers, IT contractors, and software developers invoicing through a corporation
Incorporated Professionals
Lawyers, accountants, engineers, and consultants operating through a professional corporation
Real Estate Investors
Portfolio owners and landlords where rental income adds complexity to mortgage qualification
Why business owners work with us
Banks have limited self-employed mortgage options. We shop different lenders to find the best mortgage for you and your business income.
Focused on self-employed mortgages
Licensed across Alberta & British Columbia
My service is free to you. The lender pays my fee. You get professional guidance at no cost.
Your new home in three easy steps
No more visiting multiple banks to find the best self-employed mortgage.
Share a Few Details
Complete a quick online application in under 5 minutes. We only ask for what we need to help find the best self-employed mortgage for you.
We shop multiple lenders
We compare your self-employed mortgage options across Canada’s top banks, credit unions, and alternative lenders on your behalf.
Close Your Way
Pick the self-employed mortgage option that fits your goals. We take care of the details so you can save thousands without the stress.
Licensed, regulated, and trusted across Alberta & British Columbia
Real Estate Council of Alberta
Mortgage Professionals Canada
BCFSA Agent License: 501380

We help Canadian business owners who:
Are looking to work with a self-employed mortgage professional
Have lower taxable income due to business write-offs
Have inconsistent self-employed income
Have a lower credit scores
Best Mortgage Lendersfor Self-Employed Canadians
(A vs B vs Private)
Understanding how A-lenders, B-lenders, and private lenders are different is important when you are self-employed. The guide below helps break down the difference between self-employed lender options.
| A-Lenders | B-Lenders | Private Lenders | |
|---|---|---|---|
| Who | Big banks, credit unions, monoline lenders | Alternative lenders/ programs (Home Trust, Equitable Bank, etc.) | Mortgage Investment Corporations |
| Rates | Great Rates | Slightly Higher - Good rates (closer to banks posted rates) | Much Higher Rates (9-15%) |
| Min Down Payment | 5% - 10% | 20%+ | 20% - 35%+ |
| Min Credit Score | 600 - 680+ | 500+ | No minimum (equity based) |
| Income Verification | Full or stated (select lenders) | Stated or alternative documentation | Minimal to none |
| Self-employed Friendly | Varies widely | Very | Yes |
| Fees | None | 1% - 2% one time lender set-up fee (typically) | 1% - 5% lender fee + broker fees (typically) |
| Lender Pros | Lower rates, well known lenders, no fees | Qualify for more, pay less taxes, qualify faster, less tax planning required | fast, easy, low docs, no income required |
| Lender Cons | Qualify for lower amount, strict guidelines, pay more in taxes, more tax planning required (typically) | slightly higher rates, fees, larger min down payment | expensive, larger down payment required |
My approach: I begin with A-lenders to secure the best rates and terms whenever possible. If A-lenders are not a fit, I move to B-lenders well-established institutions that offer more flexibility at slightly higher rates. Private lending is considered a last step, typically used as a short-term (1–2 year) solution when it makes strategic sense.
Did you know: Many B-lenders are actually A-lenders that offer specialized B mortgage programs designed to help business owners qualify.
Areas we serve
Serving self-employed borrowers across Alberta and British Columbia
I work with clients across Alberta and British Columbia. Local mortgage decisions still depend on the property, borrower and lender.
Alberta Service Areas
Explore city-specific resources for business owners in Calgary, Red Deer, Edmonton and surrounding communities.
Calgary | Red Deer | Edmonton | Lethbridge | Canmore | Airdrie | Chestermere | Cochrane | Medicine Hat | Fort McMurray | Okotoks
British Columbia Service Areas
Explore city-specific resources for business owners in Kelowna, Vancouver, Kamloops and surrounding communities.
Vancouver | Surrey | Burnaby | Richmond | Abbotsford | Kelowna | Kamloops | Prince George | Victoria | Okanagan | Lowe Mainland | Interior BC
Alberta & British Columbia Self-Employed Mortgage FAQs
These answers cover the most common questions from incorporated business owners, contractors, sole proprietors and other self-employed borrowers across Alberta and British Columbia. Exact lending rules vary by program and can change.
Can I get a mortgage if I'm self-employed in Alberta or British Columbia?
Yes. Being Self-employed does not prevent you from getting a mortgage. Lenders review your income, credit, down payment, existing debts and the property. The documentation and qualifying income calculation may differ from those used for salaried applicants.
How many years do I need to be self-employed?
When you are self-employed in Alberta & British Columbia two years of history is common for traditional mortgage qualification, but some programs may consider newer businesses, especially with relevant prior experience and supporting documentation. Requirements vary by lender.
Can I qualify for a mortgage if my personal tax returns show low income?
In many cases, yes. Depending on the lender and mortgage program, eligible income add-backs, corporate financial statements, down payment and credit profile may allow you to qualify for a substantially larger mortgage than your personal tax returns alone would suggest.
A low taxable income doesn't necessarily mean you have limited mortgage options. Some lenders can look beyond your personal tax returns to assess your full financial picture, potentially allowing you to qualify for a higher mortgage amount.
Can lenders use retained earnings from my corporation to help qualify for a mortgage?
Yes, some mortgage lenders may consider retained earnings within your corporation when qualifying ofr a mortgage. Depending on the lender and mortgage program, your corporate financial statements, business profitability and ownership structure may help demonstrate additional qualifying income beyond what appears on your personal tax returns.
Retained earnings are not automatically considered personal income, but they can play an important role in assessing your overall financial picture.
Do lenders accept dividends instead of salary?
Yes, many mortgage lenders accept dividend income when qualifying self-employed borrowers for a mortgage. Depending on the lender and mortgage program, they may review your T5 slips, personal tax returns, corporate financial statements and overall business profitability to determine how much income can be used.
Lenders may also assess the consistency and sustainability of your dividend payments to ensure the income can support your mortgage over the long term.
What if my business income changes each year?
Fluctuating income is common for self-employed individuals and business owners, and it doesn't automatically prevent you from qualifying for a mortgage.
Many mortgage lenders review your income over the past two years, including your personal tax returns & corporate financial statements. Depending on the lender and mortgage program, they may use a two-year average, consider income trends or review the reasons behind significant fluctuations.
Even if your income varies considerably from year to year, different lender qualification methods may help you secure a mortgage based on your overall financial picture.
Can I refinance my home if I'm self-employed?
Yes, if you meet the selected lender's income, equity, credit and other requirements. Refinancing may involve appraisal, legal costs or mortgage penalties. Explore our mortgage services for the refinance guide.
Can I buy my first home as a self-employed person?
Yes. Your lender will review qualifying income, down payment, debts and credit. First-time buyer programs may also apply, subject to eligibility. Read about first-time buyer mortgages.
How much down payment do I need for a self-employed mortgage?
The minimum down payment for a self-employed mortgage depends on the purchase price, your income documentation, credit history, property type and the mortgage program you qualify for.
In Canada, eligible borrowers may qualify for an insured mortgage with as little as 5% down on the first $500,000 of the purchase price and 10% on the portion above $500,000, up to the applicable insured mortgage price limit.
However, if your personal tax returns don't accurately reflect your business income, some alternative or stated-income mortgage programs may require a larger down payment, often 10% to 20% or more, depending on the lender.
**Being self-employed doesn't automatically mean you need a larger down payment.** The key is finding a lender that can properly assess your income and financial situation.
Can I qualify for a mortgage after being declined by my bank?
Yes, being declined for a mortgage by your bank doesn't necessarily mean you can't qualify with another lender.
Different mortgage lenders have different guidelines for assessing self-employed income, credit history, debt ratios and property types. While one bank may decline your application based on the income reported on your personal tax returns, another lender may consider corporate financial statements, eligible income add-backs or alternative income qualification programs.
A bank decline doesn't mean you're out of options. Understanding why your application was declined is the first step toward finding a mortgage lender and program that better suits your financial situation. Approval remains subject to lender requirements.
What is the best mortgage lender for a self-employed borrower?
The best mortgage lender for a self-employed borrower depends on how you earn your income, your business structure, credit history, down payment and overall financial situation.
Different lenders have different guidelines for qualifying self-employed income. While some primarily rely on personal tax returns, others may consider corporate financial statements, dividend income, eligible income add-backs or alternative income qualification programs.
The lender offering the lowest interest rate isn't always the best choice. The goal is to find a mortgage lender that understands your business income, offers competitive rates and terms, and provides a mortgage solution that fits your financial needs.
Get in Touch
Let’s Find the Best Mortgage for You
A short discovery call is all it takes to start. We'll review your situation, walk through your options, and give you a clear picture of what's possible.
Call or Text
(403) 968-8512
owen@mortgageconnection.ca
Schedule a call
Book a call for a time that works best for you